You can build financial freedom from scratch. It is not only possible, it is a far more common situation than you might imagine. What counts is not the starting point, but the way you move forward from it.
What does "starting from scratch" really mean?
Before trying to build financial freedom from scratch, it is worth looking that starting point in the face: what it really covers, and what it does not say about you.
No savings, no assets, sometimes debt
Starting from scratch financially is a concrete reality for many people: no substantial savings account, no investments, sometimes consumer debt or a recurring overdraft. It is neither a source of shame nor a personal failure, simply one starting point among others.
What starting from scratch doesn’t mean
Starting from scratch financially does not mean starting without resources. The time ahead of you, the ability to learn and consistent effort are far more powerful assets than they seem. A 25-year-old without a single franc put aside has an advantage that no amount of money can buy: several decades for time to work in their favour.
The first steps, in the right order
Where do you begin when you are starting from scratch? Whether you are aiming for financial freedom or simply peace of mind, the goal matters less than the order, because each step prepares the next.
First, see your situation as it is
Before saving or investing anything, it helps to take an honest look at your income, your expenses and any debt you may have. Not to judge yourself, but to have an accurate map of reality. A simple method takes four steps:
- Write down your net income for the month.
- List your fixed expenses, such as rent, health insurance and subscriptions.
- Go through your statements for the last three months to estimate your variable expenses.
- Note down each debt with its amount and interest rate.
Set aside a first cushion
The next priority is to build a small safety cushion. According to the Federal Statistical Office, in 2024 one in four people in the lower middle income group lived in a household unable to cover an unexpected expense of CHF 2,500.
A first milestone, for example CHF 500, already changes a great deal. It lets you absorb a small unexpected cost, such as a repair or a surprise bill, without falling back into debt. It also brings real peace of mind. The simplest way is often to set up a small automatic transfer to a separate account as soon as your salary arrives.
Pay off high-cost debt first
High-interest debt (credit cards, consumer loans, expensive leasing) should then be dealt with before saving more or investing. Interest paid is a certain cost, whereas the return on an investment never is.
The Swiss authorities' official portal explains that public debt counselling services exist in every canton. They can help you draw up a budget that should, in principle, allow you to clear your debts within three years.
Then complete your reserve
Once costly debt has been paid off, the reserve can gradually be built up to a few months of regular expenses. The right amount depends on how stable your income is, on your fixed costs and on your family situation. This emergency fund stays separate from the savings meant for investing, because it must remain available immediately.
Building up gradually, even with little
You can start saving with no starting capital. It calls for a change of perspective: you are not looking for a starting sum, you are looking for a habit.
Consistency matters as much as the starting point
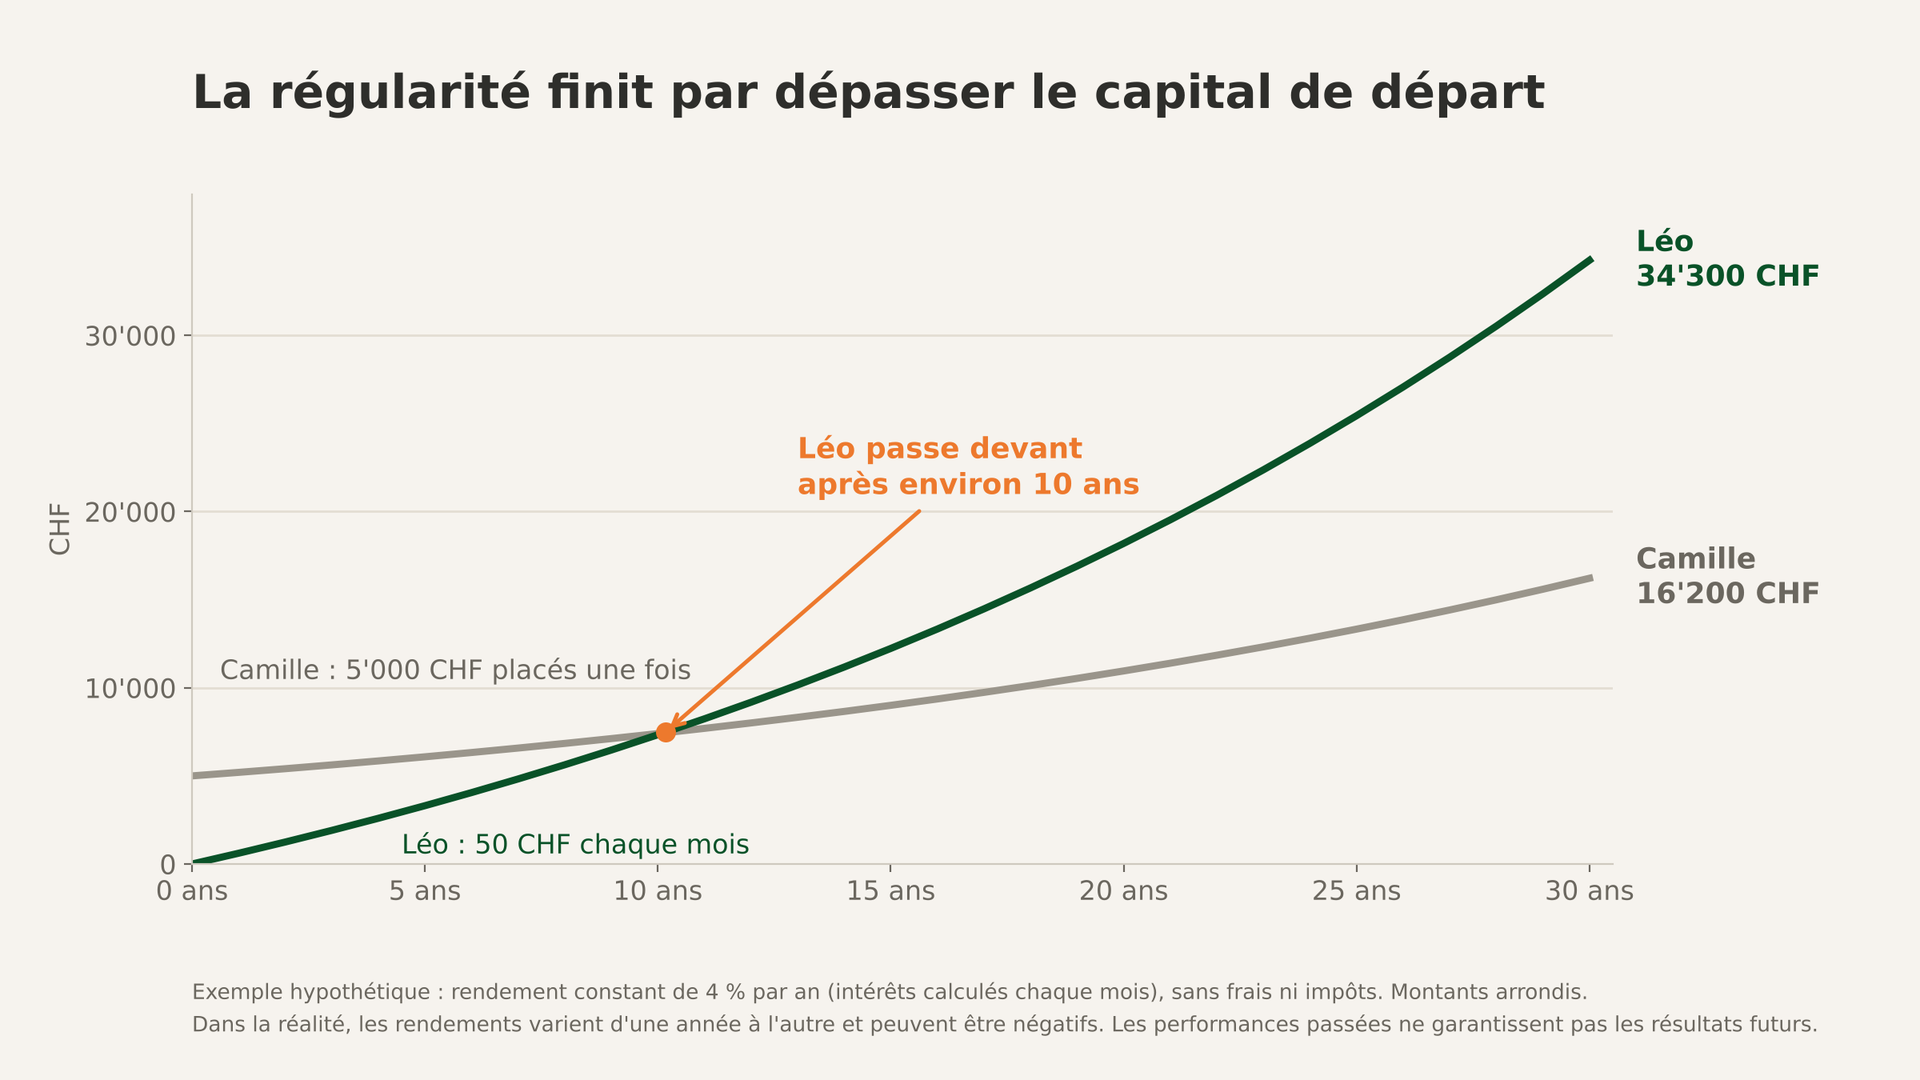
Let's take two fictional examples. Léo, 28, has no savings. Once his reserve is in place, he invests CHF 50 every month, without ever stopping. Camille received an inheritance of CHF 5,000, which she invests in one go, before never looking after her finances again.
With a hypothetical return of 4% a year for both, Camille is clearly ahead in the early years. After 5 years, she has about CHF 6,100, compared with CHF 3,300 for Léo. But every month Léo adds money, and each of his contributions starts earning interest too. After about ten years the situation reverses, and after 30 years Léo has about CHF 34,300, compared with CHF 16,200 for Camille.
The reason is not a smarter investment. It is that he never stopped: over 30 years, he paid in CHF 18,000, compared with CHF 5,000 for Camille. This is often how you can build wealth, not by waiting until you have a large sum, but by starting with what you have.
This example does not take fees or taxes into account. Real returns vary from year to year and can be negative.
Start learning while you build
There is no need to wait until you have money set aside to learn how to make it grow later. Understanding the basics, such as what a budget is, how saving works or what the main principles of investing involve, is possible today and free of charge.
Knowing where to begin when you are new to investing, even before you invest your first franc, also helps you avoid many costly mistakes.
The mindset that makes the difference
On social media, you often come across promises of quick results. Reality is slower, and that is precisely where mindset matters as much as method.
Accept that the beginning is slow
The first years of building your finances often seem unspectacular. That is normal: these are foundations, not yet results. This phase deserves patience rather than discouragement, because it is exactly when the habits that will make all the difference over ten or twenty years are formed. It is by building your financial independence step by step that you make it last.
Every decision counts, however small
No single big decision changes a financial path. It is the succession of small, consistent decisions: cancelling an unnecessary subscription, automating a transfer of CHF 50, turning down a consumer loan for a purchase that can wait. Each one seems tiny on its own.
Repeated over time, these decisions build real financial freedom. It is also why starting early counts for more than starting big.
Conclusion
Starting from scratch is not a disadvantage. It is an honest starting point, shared by many people who are building real financial independence today.
The path follows a simple order: see your situation clearly, set aside a first cushion, pay off the most expensive debt, complete your reserve, then move forward consistently. What makes the difference is the decision to act now, even modestly, rather than waiting for perfect conditions that will never come.
Starting today, write down your income and fixed expenses for the month, or set up an automatic transfer, even of CHF 20, to a separate account.
You don't need to sort everything out at once. What matters is to start.
To get started: the Academy's Foundations programme, free, helps you lay the groundwork for your financial freedom, at your own pace.
To go further: the AdvisorOne Diagnostic takes a few minutes to show you where you stand, with no commitment.
FAQ
How can you save when you have almost nothing?
By starting with a realistic amount, even CHF 20 or 50 a month, and automating it as soon as your salary comes in. Consistency matters more than the starting amount: it is the habit that builds the path, not the initial sum. If your budget is really tight, starting with CHF 10 is still a real start.
Can you invest with no starting capital?
Yes. Many savings and investment solutions let you start with small regular amounts rather than a large lump sum. What matters is to start, even modestly, rather than waiting until you have "enough", once you have paid off costly debt and built your reserve.
Where do you start when you have debt?
With high-interest debt. List your debts from the highest interest rate to the lowest, then focus your repayments on the first one while paying the minimum on the others. If the situation becomes hard to manage alone, a specialised debt counselling service can help you negotiate with your creditors and get back to a manageable budget.
How long does it take to build real financial freedom?
There is no universal timeframe: it all depends on what you mean by financial freedom and on your situation. For some people, the first form of freedom is simply getting out of their overdraft and having an emergency fund. In any case, it usually takes years rather than months, but every step brings you concretely closer to the goal.
Is it too late if you start at 40?
No. The time ahead of you is still a valuable ally, even if it is shorter than at 25. At 40, there are generally more than twenty years left before retirement. What counts is starting with a clear method and staying consistent, whatever age you start at.
⚠️ Important notice ⚠️
The information presented in this article is provided for purely informational and educational purposes. It does not in any way constitute a personalised recommendation, investment advice, an offer or a solicitation to buy or sell financial products.
Any investment decision should be made after a thorough analysis of your personal situation, your objectives and your risk profile, and may require the advice of an authorised financial adviser.
Past performance is no guarantee of future results. Investments involve risks, including the risk of capital loss.